Where is Asian oil MR freight heading?
Our Dubai brokers and our Research team compared notes: market instinct on one side, data analysis on the other. Here’s what they see.
Riverlake MR Global Market Snapshot
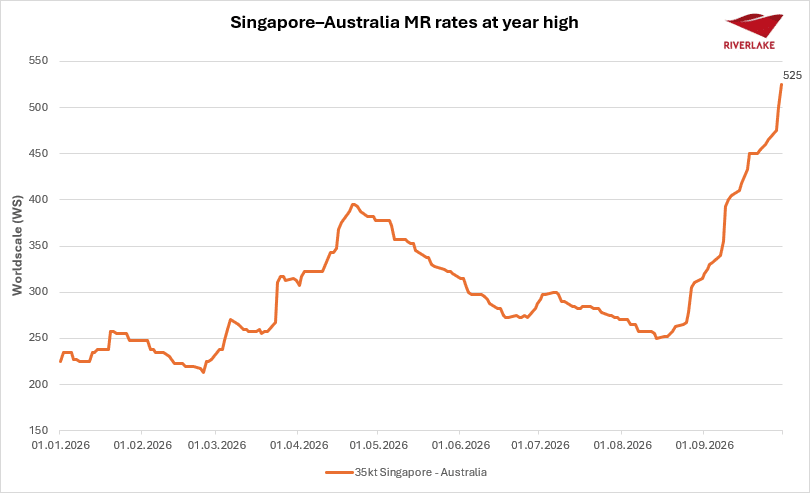
Owners remain confident that the market will continue to hold at current levels. There could be a small correction, but expect the market to remain at relatively high levels.
Atlantic
US stocks are currently at very low levels. The issue is that the storage facilities/caverns are so depleted that the product remaining at the bottom is contaminated with a mixture of mud and sediments, making it very costly to clean and recover. The lower the inventory levels, the more expensive it becomes to extract the remaining product.
This is one of the reasons why the threat of an export ban could be considered plausible.
One view is that the Atlantic market could rebound, which would reduce the incentive created by the Pacific/Atlantic arbitrage for owners to reposition vessels back into the Pacific. This is particularly relevant given that the Panama Canal transit is still costing more than $5 million, assuming you are fortunate enough to secure a transit slot.
As a result, tonnage is likely to remain tight in the Pacific.
Pacific
In the AG MR market, sentiment has become increasingly bullish, with regional vessel supply remaining tight. Cargoes for early October are still being worked, while activity in East Asia remains healthy.
In the short term, East Asia remains firm, although activity could be impacted by China’s upcoming long holiday. Vessel supply remains tight and cargoes continue to be worked. Delays in Southeast Asia, due to congestion, are pushing charterers to look for replacement vessels. With tonnage remaining limited, charterers are being forced to accept rates which continue to rise as they have little choice but to lift the cargo.
As long as China continues to export, market levels are expected to remain elevated. The demand destruction due to high end-consumer prices might be the correction factor.